
Showing posts with label banking terminology. Show all posts
Showing posts with label banking terminology. Show all posts
Sunday, February 15, 2015

Friday, January 30, 2015
Important Facts about Indian Currency-Banking terminology
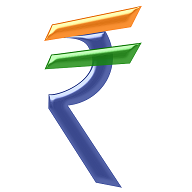 The Indian rupee symbol '
 ' (officially adopted in 2010) is derived from the Devanagari consonant "र" (ra) and the Latin letter "R". The first series of coins with the rupee symbol was launched on 8 July 2011. Currency paper is composed of cotton and cotton rag.
RBI issues all the bank notes except Rupees 1 Notes. These notes are issued by Ministry of Finance. Recently RBI launched a website Paisa‐Bolta‐Hai to raise awareness of counterfeit or fake currency among users of the Indian Rupees and also the citizen of India.
The main security features of current banknotes are:
- →Watermark ‐ White side panel of notes has Mahatma Gandhi watermark.
- →Security thread ‐ All notes have a silver or green security band with inscriptions (visible when held against light) of Bharat in Hindi and "RBI" in English.
- →Latent image ‐ On notes of denominations of Rs.20 and upwards, a vertical band on the right side of the Mahatma Gandhi’s portrait contains a latent image showing the respective denominational value numerally (visible only when the note is held horizontally at eye level).
- →Micro lettering ‐ Numeral denominational value is visible under magnifying glass between security thread and latent image.
- →Intaglio ‐ On notes with denominations of INR5 and upwards the portrait of Mahatma Gandhi, the Reserve Bank seal, guarantee and promise clause, Ashoka Pillar Emblem on the left and the RBI Governor's signature are printed in intaglio (raised print).
- →Identification mark ‐ On the left of the watermark window, different shapes are printed for various denominations INR20: vertical rectangle, INR50: square, INR100: triangle, INR500: circle, INR1,000: diamond). This also helps the visually impaired to identify the denomination.
- →Fluorescence ‐ Number panels glow under ultraviolet light.
- →Optically variable ink ‐ Notes of Rs.500 and Rs.1,000 denominations have their numerals printed in optically variable ink. The number appears green when the note is held flat, but changes to blue when viewed at an angle.
- →See‐through register ‐ Floral designs printed on the front and the back of the note coincide and perfectly overlap each other when viewed against light.
- →EURion constellation ‐ A pattern of symbols found on the banknote helps software detect the presence of a banknote in a digital image, preventing its reproduction with devices such as colour photocopiers.
Different Kinds of Notes:
- →Genuine Notes: Such notes must have a water mark of Asoka Pillar, security thread and serial number along with alphabet. They have distinctive colours.
- →Soiled notes: The currency note which has become dirty due to its use or may be in 2 pieces. No portion of such note should be missing. These notes are accepted for exchange without any restrictions by the banks.
- →Mutilated notes: Such currency notes that are composed of various pieces or they are cut note of which some portion is missing. These notes are exchanged only by the currency chest branches of banks.
- →Single/double numbered notes: Notes up to Rs.5 are single numbered while the notes above Rs.5 are double numbered notes.
RBI’S Clean Note Policy
RBI had announced ‘Clean Note Policy’ in January, 1999.
For withdrawing soiled notes from circulation and pumping fresh notes into circulation, the RBI introduced various changes in the system and procedures related to currency management which include mechanization of the currency verification and processing as also shredding and briquetting for destruction of soiled and mutilated notes.
Rules and Instructions Issued by RBI:
→Not to staple bank notes.→To Tender soiled notes to the Reserve Bank in unstapled condition.
→To use bands instead of staple pins.
→To issue only clean notes to members of public.
→To open select currency chest branches on Sundays to provide exchange facility to members of public all over the county.
→To provide unrestricted facility for exchange of soiled and mutilated notes to members of public.
→Banks should sort notes into re‐issuables and non‐ issuables, and issue only clean notes to public.
→Soiled notes in unstapled condition may be tendered at RBI in inward remittances through Currency Chests.
→Banks should stop writing of any kind on watermark window of bank notes.
Coins of 25 Paise and Below – Withdrawal
→Govt, of India has decided to withdraw the coins of 25 paise and below from circulation from June 30, 2011. Coins of 25 paise and below are not accepted for exchange at the bank branches from July 1, 2011 onward.
Withdrawal of Pre‐2005 Notes:
→Reserve Bank of India decided to withdraw from circulation all banknotes issued prior to 2005 as they have fewer security features as compared to banknotes printed after 2005.
→The withdrawal exercise is in conformity with the standard international practice of not having multiple series of notes in circulation at the same time.
→The RBI has already been withdrawing these banknotes in a routine manner through banks.
→It is estimated that the volume of such banknotes (pre‐2005) in circulation is not significant enough to impact the general public in a large way and the members of public may exchange the pre‐2005 series banknotes at bank branches at their convenience.
→The deadline for exchanging pre‐2005 currency notes of various denominations, including Rs.500 and Rs.1,000, has been extended by another six months till June 30, 2015.
Saturday, January 24, 2015
Difference between Savings and Current Account
 Many people get confused while withdrawing money from ATM when the see the chose "Current Account or "Savings Account".
They both are different type of accounts offered for different purposes. Now, let us know the basic difference between savings account and current account.
Savings Account
As the name indicates, this account is meant for saving purposes. Any individual either single or jointly can open a savings account.
In these accounts one has to maintain minimum balance as low as Rs1000/ in some PSU banks while it is Rs 10,000 and above in private sector banks. In savings account number of financial transactions are restricted.
Interest rates are higher when compared to current account. Any cash transactions of Rs 10 lakhs and above in a year will be informed to the IT department.
In case, if you do many cash transactions and issuing of cheques in a savings account, banks have all the right to question you on the income and reason for transaction.
Current Account:
Current account is mainly for business persons, firms, companies, public enterprises etc. This is useful when a person does a number of business transaction on daily basis.
While, there is no interest paid on amount held in the account, there is no limit on number of transaction.
In case of ATM withdrawal if you have a salary account or zero balance account you should opt for the savings account.
| Savings Account | Current Account | |
| Purpose | To encourage saving | Many transaction |
| Ideal for | Salarised person | Business person |
| Minimum Amount | Less amount | Heigher amount(depending on the bank) |
| Interest Rates | 4% - 6% | Normally, no interest is paid |
| Over Draft | Not Allowed | Allowed |
Friday, January 23, 2015
What does Balance Sheet means in Banking Terminology
 Balance Sheet in Banking Terminology means?
Balance Sheet:
The balance sheet is an accounting statement that summarizes the various assets, liabilities and equities held by a company on a specific date.
The equities are usually considered as part of the liabilities. The balance sheet is always drawn up at the close of business day, but is most relevant on the last day of the company's accounting period (the balance sheet date).
The equities are usually considered as part of the liabilities. The balance sheet is always drawn up at the close of business day, but is most relevant on the last day of the company's accounting period (the balance sheet date).
Balance Sheet Importance:
Balance sheet is an important documents not only for bank managers who sanction loan but is equally important to others who give credits and invest in equity etc. All creditors and investors all need to familiarize themselves with the assets, liabilities, and equity of a company. The balance sheet is the best place to find all information at one place. The reason as to why balance sheet is so called is that it is statement where Assets = Liabilities + Equity
Difference between crossed Cheque and Account payee Cheque

What is the Difference between crossed Cheque and Account payee Cheque ?
Cheque Cheque.
In case of a crossed cheque, the payee is free to make further endorsements.
For example , Ayesha receives a check from Rohan which has been crossed, Ayesha can get this payment in her account only and not across the counter. But in this case Ayesha is free to endorse the cheque in favor of Suresh and further Suresh is free to endorse the instrument in favor of Mukesh and so on…This means that crossing a cheque does not put restrictions on endorsements. In case the Cheque gets dishonored, Mukesh can sue Suresh and Suresh can sue Ayesha and Ayesha can sue Rohan
Account payee Cheque.
But, the A/C payee Cheque cannot be further endorsed. This means that if the Cheque in the above example which is in favor of Ayesha bears “A/C Payee”, payment can be collected in Ayesha’s account only. The paying bank makes sure that amount is being credited to the account of the payee only
Subscribe to:
Posts (Atom)